

Key highlights:
- Vitalik Buterin argues ETH should prioritize its store-of-value potential over fee burning, citing Ethereum’s decentralization, security, and censorship resistance
- Buterin says Ethereum’s historical fee burns were largely driven by crypto-native activity, making them an unreliable foundation for ETH’s long-term valuation
- The Ethereum co-founder warns that maximizing transaction fees could undermine decentralization and accessibility, arguing that ETH’s value should come from the network’s long-term stability and resilience
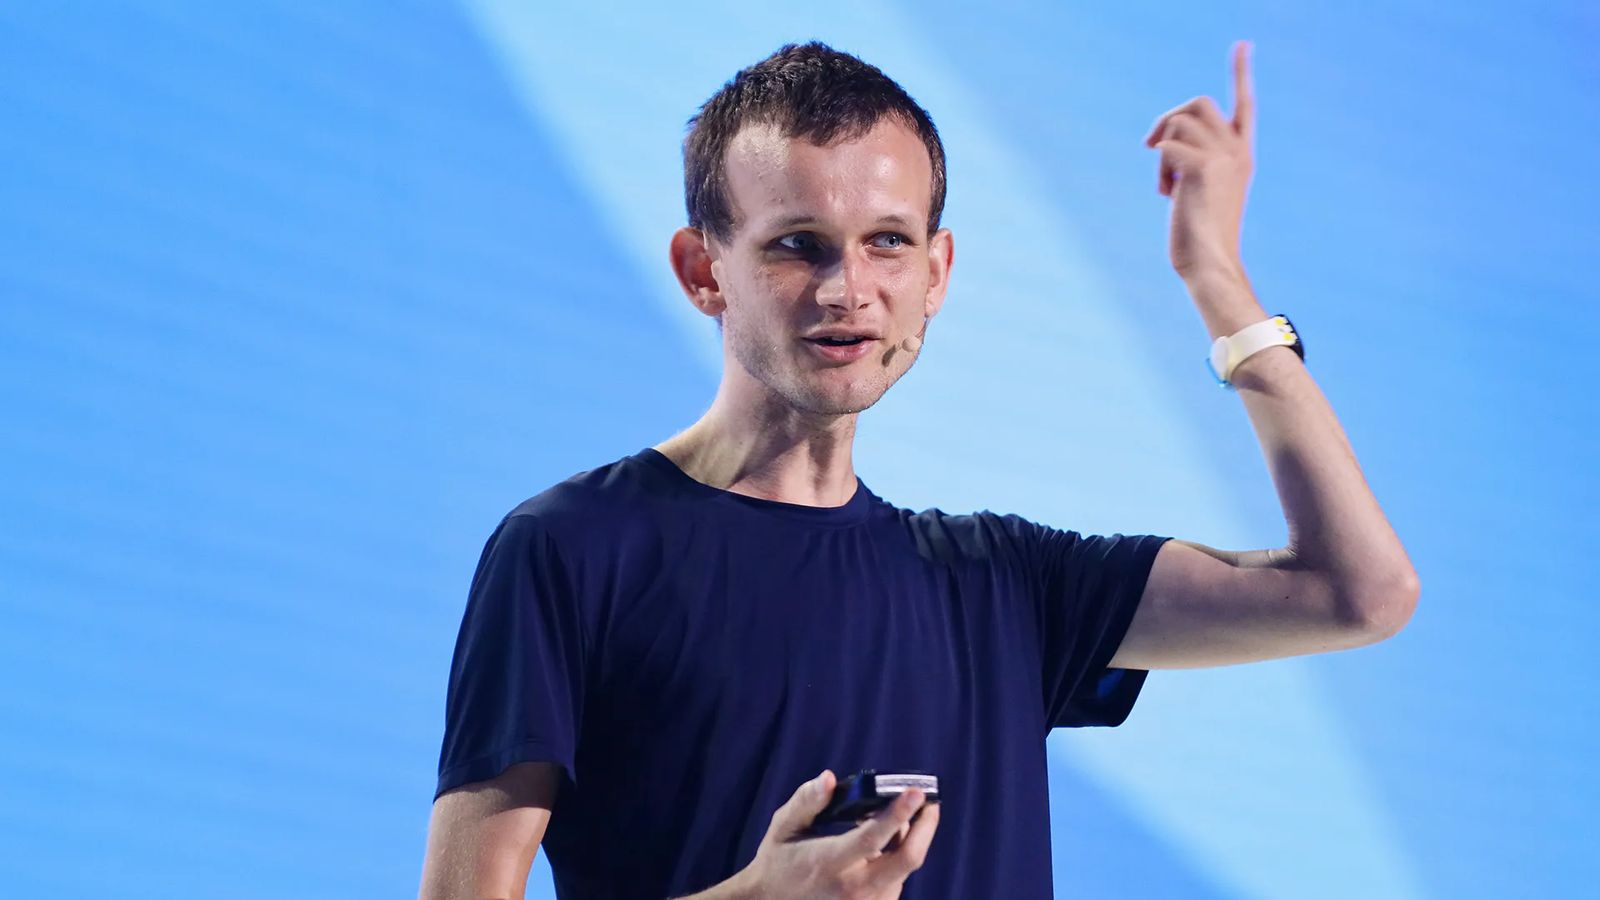
Ethereum co-founder Vitalik Buterin has argued that ETH should be positioned primarily as a store of value rather than a fee-burning asset. Vitalik’s position challenges a popular investment narrative built around the network’s EIP-1559 fee mechanism as investors scan the horizon for higher ETH prices.
Vitalik Buterin questions the economics of ETH fee burning
In a lengthy post on X, Buterin said Ethereum’s long-term value comes from its decentralization, censorship resistance, privacy, and security rather than the amount of ETH destroyed through transaction fees. He argued that prioritizing fee generation could undermine the very properties that make Ethereum valuable
Buterin challenged the idea that Ethereum’s fee-burning mechanism provides a reliable valuation floor for ETH.
Under EIP-1559, Ethereum burns a portion of transaction fees, permanently removing ETH from circulation. During periods of intense network activity, particularly between 2021 and 2023, the mechanism resulted in millions of ETH being destroyed.
The economic argument behind this model is that sustained fee burning creates a predictable stream of value for ETH holders. Using a net present value framework, Buterin explained that a token burning $1 billion annually could theoretically justify a $25 billion valuation at a 4% discount rate.
However, the Ethereum co-founder argued that this valuation framework has a major weakness because much of Ethereum’s historical fee generation came from crypto-native activities.
If ETH’s price fell significantly, the purchasing power of participants in these activities would also decline, potentially reducing the fees generated by the network. This means the revenue stream is not necessarily independent of ETH’s market value.
Buterin acknowledged that the growing real-world asset (RWA) economy could provide Ethereum with stronger external sources of economic activity. However, he questioned whether these relatively stable businesses could generate the extraordinary fee levels seen during speculative periods.
Chasing fee revenue could undermine Ethereum’s decentralization
Buterin also warned that optimizing Ethereum for fee generation could push the network toward a corporate-style operating model.
He compared Ethereum’s approximately $270 billion market capitalization to that of major global corporations, arguing that businesses of comparable scale must continuously invest in research, development, and new products to maintain their market positions. According to Buterin, Ethereum would need substantially more funding and interventionist governance to pursue a similar strategy.
He estimated that matching L’Oreal’s research and development spending as a proportion of market capitalization would require approximately 700,000 ETH annually. Such funding would introduce significant political and governance challenges while potentially reducing validator rewards.
He also argued that maximizing transaction fee revenue could encourage higher gas prices, potentially excluding users who depend most on affordable access to privacy and security infrastructure.
Ethereum’s long-term value lies in its store-of-value properties
Instead of maximizing fee burns, Buterin wants Ethereum to prioritize the characteristics that make ETH attractive as a long-term store of value. He identified decentralization, censorship resistance, open-source infrastructure, privacy, and security (CROPS) as Ethereum’s most important competitive advantages.
According to Vitalik Buterin, these properties translate into stability, which is particularly important for individuals and institutions holding substantial assets.
Buterin pointed to several ongoing development efforts that support this direction, including multisignature wallets, the Kohaku privacy initiative, private account abstraction, and FOCIL, which aims to strengthen censorship resistance.
He also highlighted Ethereum’s efforts to prepare for post-quantum and post-AI threats, arguing that a durable store of value must prioritize long-term security and conservative protocol design.
The growing adoption of real-world assets and decentralized financial applications could further strengthen ETH’s position by expanding the range of assets users can access, trade, and use as collateral.
Buterin clarified that he supports keeping EIP-1559 and its fee-burning mechanism. However, he argued that Ethereum should not be concerned if fee burns remain below 10% of the network’s breakeven level indefinitely.